

Welcome back to IPO season.
No, we will not call it hot liquidity summer, but after an August lull, the public-offering cycle is back upon us. Last week we saw filings from Warby Parker, Toast and Freshworks. We have actually dug into Warby currently. This week, we’re taking on the details of the latter two launchings, starting with Toast.
The Exchange explores startups, markets and money.
Read it every morning on Bonus Crunch or get The Exchange newsletter every Saturday.
Why do we care about Toast? It’s an innovation startup. It’s a unicorn. And it raised more than $900 million while personal, per Crunchbase data. And the company is a leading constituent of the Boston startup scene.
A lot more, the software-and-payments company combines membership incomes, transaction costs, hardware earnings and lending profits. Its service is intricate — — in a great way — and may assist us better comprehend what happens to software application business when they construct more financial abilities into their original applications.
 It’s a fascinating business, one that was initially affected greatly by the COVID-19 pandemic. Let’s review the company’s general monetary performance, dig into how COVID affected the company’s business, consider how its earnings mix is altering over time, go over how important fintech earnings are for the business and what it may be worth. This will be excellent fun. Let’s
go! Toast’s growth is speeding up
We’ll carve more deeply into how the company produces earnings shortly. For now, simply remember that the business has a variety of earnings streams, each of which has a various gross-margin profile. So, we’re not just talking about high-margin software revenues in the following.
Here’s Toast’s topline performance for 2019, 2020, and the first half of both 2020 and 2021, drawn from its S-1 filing:
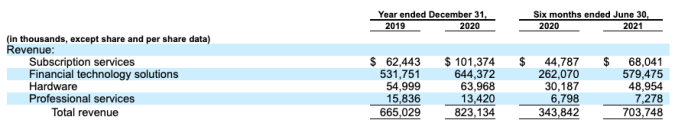
Image Credits: Toast S-1 We can quickly see that the business grew from 2019 to 2020, albeit at a moderate clip. More recently, observing the two columns on the far right, we can see much more rapid growth from the company. In year-on-year relative terms, Toast grew 24% in 2020 and 105% in the first half of 2021.
Thinking of how COVID-19 struck the food company, observing modest development at the company in 2020 feels rather strong; in spite of big market slice, Toast still grew nicely. And the business’s H1 2021 results suggest that the product work that Toast engaged in during the worldwide pandemic has worked well, enabling it to speed up development by an element of 4 in the last two quarters when compared to 2020’s overall speed of profits growth.
The above information likewise helps us much better understand why Toast is going public now. After pushing through 2020, the business’s existing portrait is among speeding up development resulting in enormous top-line accretion. Toast looks more than strong. And there’s no much better time to go public than when you have numbers to brag about.
Article curated by RJ Shara from Source. RJ Shara is a Bay Area Radio Host (Radio Jockey) who talks about the startup ecosystem – entrepreneurs, investments, policies and more on her show The Silicon Dreams. The show streams on Radio Zindagi 1170AM on Mondays from 3.30 PM to 4 PM.
Recent Comments